A burst supply line can soak flooring, drywall, inventory, and equipment in minutes. Once the immediate danger is under control, knowing how to document a water damage insurance claim can make the next steps far less uncertain. Clear records help show what happened, when it happened, what was affected, and what was necessary to prevent further damage.
The goal is not to create a perfect file while your property is under stress. It is to preserve reliable evidence, report the loss promptly, and keep the mitigation and insurance process organized. For homeowners, that protects the space and belongings that matter most. For commercial property owners and managers, it also helps support faster decisions, continuity planning, and a safer return to operations.
Start documentation before cleanup changes the scene
If the source is active, prioritize safety and stop the flow if you can do so safely. Shut off the local water supply or main water valve, move people away from electrical hazards, and contact emergency help when needed. Do not enter standing water near electrical outlets, panels, or appliances.
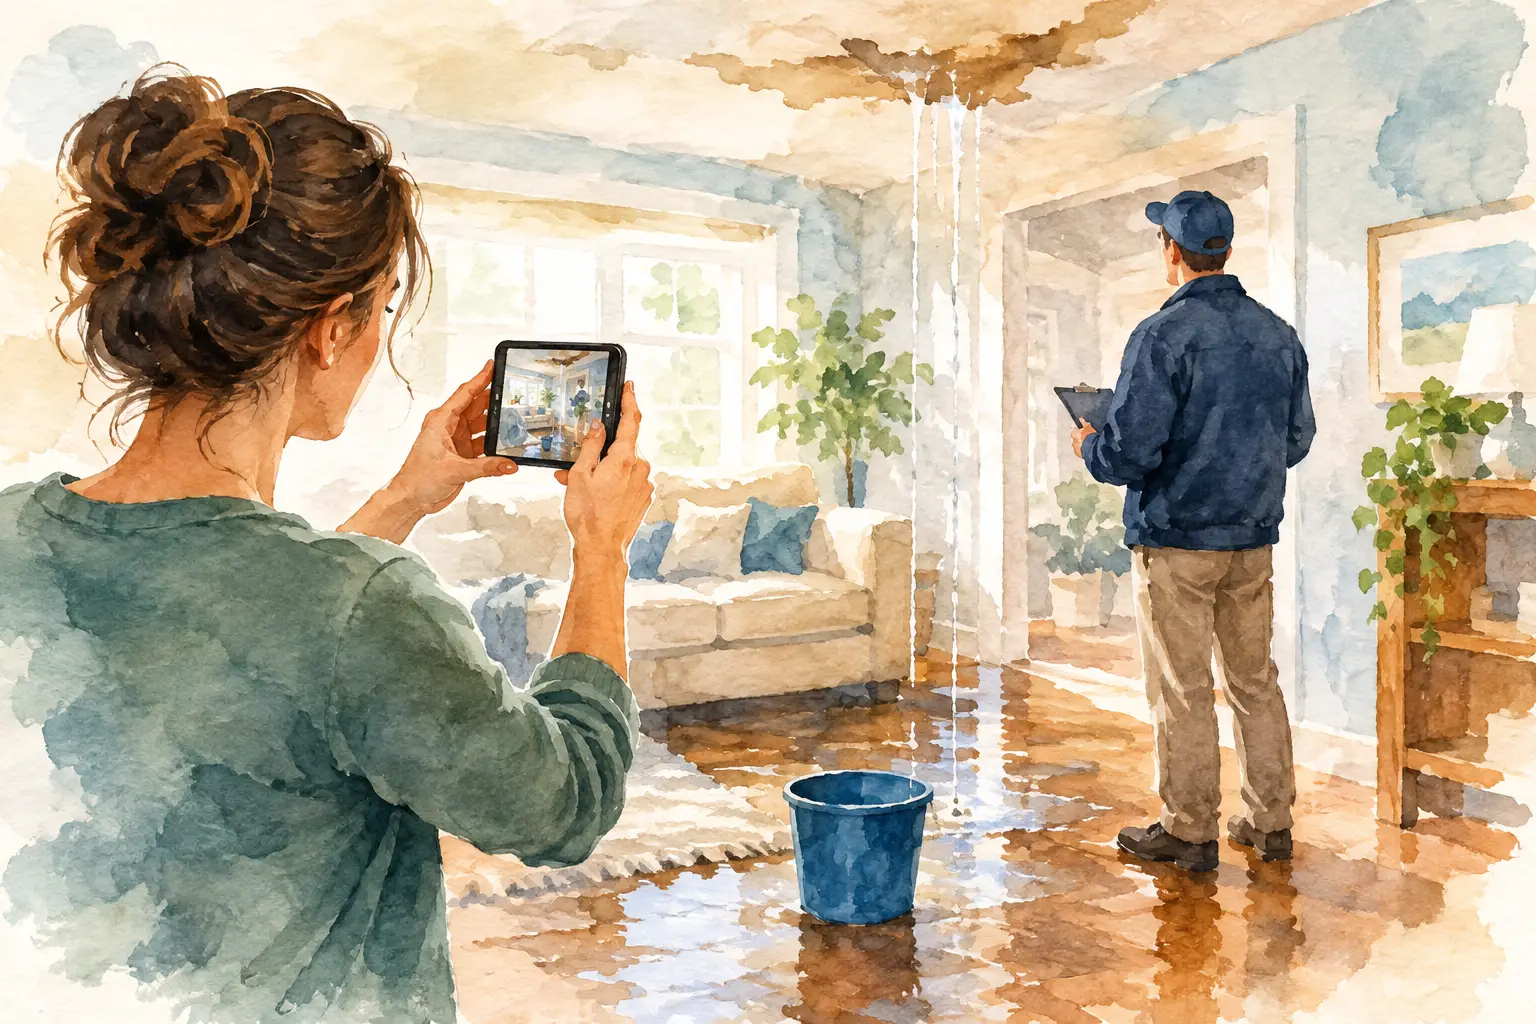
Once the immediate hazard is controlled, take wide photos and video before removing damaged materials or moving contents. Start outside the affected room or area, then work inward. A brief video walkthrough can establish context, while still photos provide clearer detail for individual items and surfaces.
Capture the source of the loss when possible, such as a failed appliance hose, leaking pipe, roof opening, overflowing fixture, or visible water entry point. Include the extent of water migration: wet baseboards, buckled flooring, stained ceilings, damaged wall finishes, affected cabinets, and impacted contents. For a business, photograph inventory, furniture, equipment, documents, stored materials, and any areas taken out of service.
Do not delay emergency drying simply to take more photos. Water can continue moving through porous materials, and mold growth can begin when moisture remains. Document what you reasonably can, then take practical steps to protect the property from additional loss.
How to document a water damage insurance claim step by step
Your claim file should tell a simple, chronological story. The insurer or adjuster needs to understand the cause of loss, the damage observed, the actions taken, and the cost to restore the affected property. Keep the original files whenever possible rather than relying only on images sent by text message.
Create a dated photo and video record
Use your phone’s standard camera settings so the date and time are retained in the image metadata. Photograph each affected room from multiple angles, then take close-ups of material damage. If water reached more than one level, document each level separately.
For high-value belongings, capture identifying details such as model numbers, serial numbers, labels, and manufacturer tags. This is especially useful for commercial equipment, electronics, appliances, and specialty items. If an item must be discarded because it is unsanitary or cannot be safely restored, photograph it before disposal and save any label or serial-number information.
Write down what happened while it is fresh
Create a timeline in a note on your phone, a spreadsheet, or a paper log. Record the date and approximate time the loss was discovered, the suspected source, when the water was shut off, and every call you made. Include the name of the person or company contacted and a short description of the response.
Also record changes you observe over the next several days. For example, you may notice water appearing in an adjacent room, flooring separating as it dries, or an odor developing after the initial event. These notes can help explain why mitigation expanded beyond the first visible area.
For commercial properties, include operational effects in the timeline. Note closed work areas, interrupted services, damaged stock, equipment downtime, canceled events, temporary relocation needs, and safety measures taken. Property damage and business interruption coverage are different issues, and coverage depends on the policy, but clear operational documentation gives your insurance representative and financial team a stronger starting point.
Make a room-by-room inventory
A broad statement such as “living room contents were damaged” is rarely as useful as an itemized record. Work through each affected space and list the item, brand or description, age if known, condition before the loss, and estimated replacement cost. Add photos beside or after each entry.
Receipts, invoices, credit card statements, appraisals, warranties, and prior photos can help establish ownership and value. Do not guess when records are unavailable. Describe the item accurately and note that the value is an estimate. Your insurer may have its own forms or preferred documentation process, so ask what information it needs.
Save every expense and mitigation record
Reasonable emergency actions can be necessary to prevent additional damage, but policies differ in what they cover and how reimbursement works. Keep receipts for materials, emergency plumbing, temporary protective measures, equipment rental, hotel stays if applicable, and other loss-related expenses. Ask before making major repairs that go beyond stabilization unless safety requires immediate action.
A professional restoration team should also provide documentation of its assessment and mitigation work. That may include moisture readings, affected-material findings, drying equipment records, daily monitoring notes, photos, and an itemized scope of work. These records help show why drying, cleaning, removal, or reconstruction was necessary rather than cosmetic.
Report the loss promptly and keep communications organized
Contact your insurance carrier or agent as soon as practical after discovering the damage. Have your policy number, date of loss, cause of loss, photos, and a brief description ready. Ask for the claim number and the preferred method for submitting documentation.
Keep a dedicated folder, digital or paper, for the claim. Save emails, claim correspondence, estimates, receipts, inspection reports, and notes from phone conversations. After a call, write down the date, the representative’s name, and what was discussed. If the insurer requests additional information, respond carefully and retain a copy of everything submitted.
Avoid throwing away damaged materials until the insurer or adjuster has had an opportunity to inspect them, unless they present a health or safety issue. If removal is necessary, photograph the material thoroughly first and retain a small sample when appropriate and safe. Sewage-contaminated water, for example, can make porous items unsafe to keep. In that situation, health protection and proper cleanup come first.
Support the inspection without overstating the damage
When an adjuster visits, provide a clear walkthrough of the affected areas, your timeline, and your documentation. Point out damage that may be easy to miss, including wet contents stored in cabinets, staining on the underside of materials, or water that traveled into adjoining rooms.
Be factual. Explain what you saw, what you did to protect the property, and what professionals found during assessment. Do not minimize damage out of concern that it may sound inconvenient, but do not speculate about causes or costs you cannot support. If the cause is still being investigated, say so.
It is also reasonable to ask questions. Confirm what documents are still needed, whether the insurer needs to inspect before certain repairs begin, and how supplemental damage is handled if concealed moisture or additional affected materials are discovered during restoration. Water losses often change as materials are opened and dried, particularly in older buildings or multi-unit properties.
Why professional mitigation records matter
Visible water is only part of the loss. Moisture can move behind walls, beneath flooring, into insulation, and through building assemblies. A restoration assessment uses moisture detection and material evaluation to identify what needs drying, cleaning, removal, or repair. That work helps protect the property, but it also creates a defensible record of conditions that may not appear in a single photograph.
ServiceMaster Restore by DCS can help property owners move from emergency assessment to mitigation and reconstruction with one accountable recovery team. For homes, warehouses, restaurants, churches, and other facilities, coordinated documentation helps keep the restoration process orderly while the insurance claim moves forward.
The strongest claim file is built in real time: photos before conditions change, notes while details are clear, receipts as expenses occur, and professional records that explain the work. Take the next safe step, preserve what you can, and focus on restoring the property rather than carrying the entire process alone.